
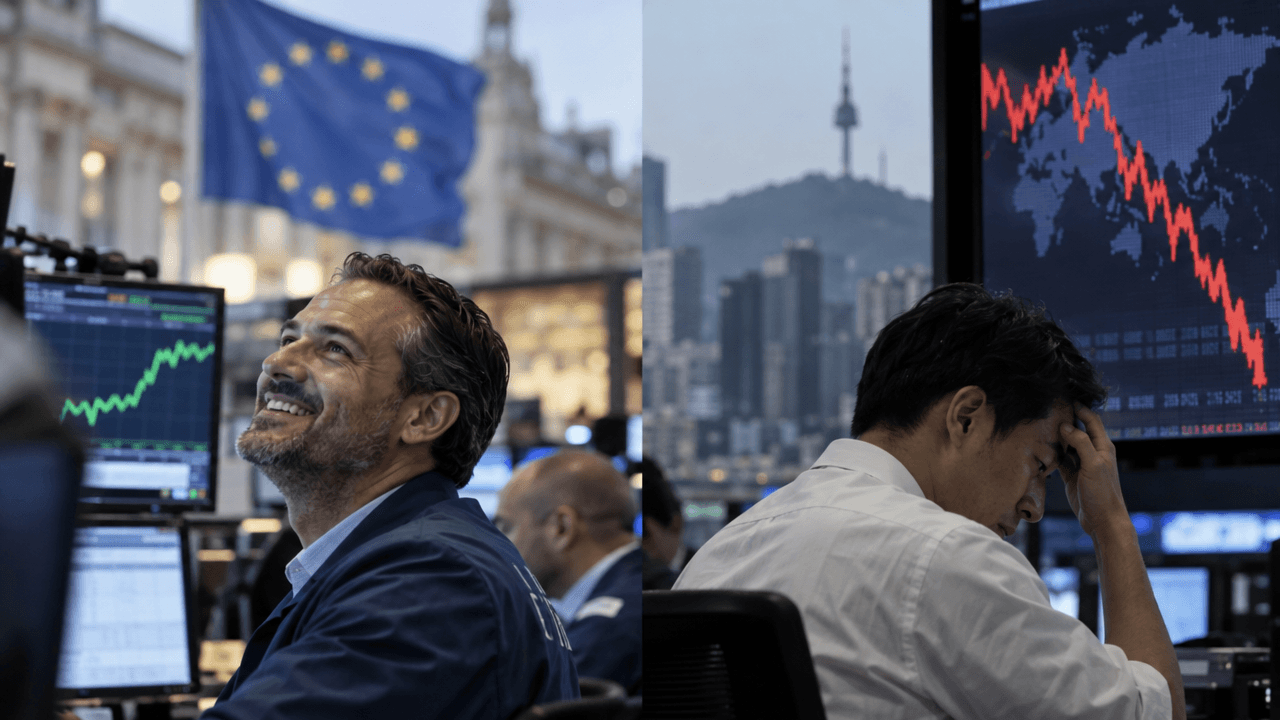
European stocks opened the week with a firmer tone, outperforming a mixed Asian session as investors reassessed risk across regions. Germany’s DAX rose roughly 0.7%, while France’s CAC 40 gained about 0.9% in early trading. By contrast, South Korea’s Kospi fell approximately 1.5%, highlighting renewed pressure on technology and semiconductor shares. [9]
The divergence reflects more than a simple regional rotation. Markets are balancing several competing forces: concern about the sustainability of artificial intelligence spending, a packed schedule of corporate earnings, upcoming central-bank decisions, and changing expectations for energy prices. For traders, Monday’s moves offered an important reminder that global equity markets may respond very differently to the same macroeconomic headlines.
EUROPE’S RELATIVE STRENGTH
European shares benefited from a combination of bargain hunting, easing oil prices, and company-specific developments. The broader Stoxx 600 rose around 0.3%, while France’s CAC 40 gained between 0.7% and 0.9% in different stages of trading. French bonds also strengthened after France avoided a credit-rating downgrade, reducing one source of pressure on the country’s financial markets. [11][12]
Germany’s DAX also advanced, recovering some ground after recent weakness. Although European markets remain sensitive to global technology sentiment, their sector composition gives them exposure to industries beyond the most crowded AI trades. Luxury goods, industrial companies, banks, energy firms, and healthcare businesses can respond to different economic catalysts than major American or Asian chip stocks.
The retreat in crude oil prices also helped improve sentiment. Oil had recently climbed to a six-month high, raising concerns about renewed inflationary pressure and the potential impact on household spending, business costs, and interest-rate expectations. A pullback in energy prices can support equities by reducing fears that central banks will need to keep monetary policy restrictive for longer.
ASIA’S MIXED SIGNAL
Asian markets presented a less consistent picture. Japan’s Nikkei and the broader Topix were relatively resilient in early trading, while Chinese technology shares and Japanese semiconductor stocks faced pressure. South Korea was the clearest weak spot, with the Kospi dropping 1.5% to about 5,469 points. [6]
South Korea’s market has significant exposure to chipmakers and other technology exporters, making it particularly vulnerable when investors question the durability of AI-related demand. The decline came as traders prepared for third-quarter results from major semiconductor companies, including Samsung and SK hynix. Those earnings will be closely watched for evidence that demand, pricing, and capital expenditure plans justify the sector’s elevated expectations. [1]
This concentration effect helps explain why the Kospi can fall even when other regional benchmarks are stable. A market dominated by a small group of high-growth companies may experience larger swings when investors rotate away from momentum trades. The same dynamic can create sharp rebounds if earnings provide reassurance.
The Ai Trade Faces A Test
The pressure on AI-linked shares is not necessarily a judgment that artificial intelligence lacks long-term potential. Instead, investors are questioning whether current valuations adequately reflect the enormous spending required to build data centers, purchase advanced chips, and expand cloud infrastructure.
The next major test will come from earnings reports by Amazon, Microsoft, and Alphabet, alongside results from leading South Korean chipmakers. Investors will examine revenue growth, cloud demand, operating margins, capital expenditure, and management commentary about the timing of returns from AI investment. [1][11]
The key issue is becoming more specific. Markets no longer want only evidence that companies are using AI. They want proof that spending is translating into measurable commercial results. If technology leaders report strong demand and credible profitability, the recent rotation could reverse quickly. If spending continues to rise faster than revenue, investors may become more selective and punish companies with weaker returns on investment.
For traders, this creates a high-volatility environment. Earnings headlines can move individual stocks sharply, but the broader market reaction may depend on guidance and forward-looking commentary rather than the headline profit number alone.
What Traders Should Watch
Several indicators deserve attention during the week. First, monitor the performance gap between European industrial and financial shares and global technology stocks. A widening gap could signal a continuing rotation toward value and cyclical exposure.
Second, watch government-bond yields and oil prices. Rising yields can pressure equity valuations by increasing the discount rate applied to future profits, while a renewed oil rally could revive inflation concerns. Conversely, stable energy prices and calmer bond markets would provide a more supportive backdrop for stocks.
Third, pay close attention to market breadth. If only a handful of shares rise while most stocks remain weak, the apparent recovery may lack durability. Stronger breadth, with gains spread across multiple sectors and regions, would offer more convincing evidence that risk appetite is improving.
Finally, traders should avoid treating one session as a definitive trend. European stocks’ outperformance may reflect temporary positioning, while Asia’s weakness may be concentrated in technology-heavy markets. The direction of the next move will likely depend on earnings, central-bank communication, and whether investors regain confidence in the economics of AI spending.
Conclusion
European stocks began the week on firmer ground than several Asian markets, but the difference reflects changing sector leadership rather than a clear regional economic victory. The DAX and CAC 40 benefited from improved sentiment, lower oil prices, and reduced concerns around French credit risk, while the Kospi suffered from its heavy exposure to semiconductor and AI-linked shares.
The market’s central question is now whether artificial intelligence investment will generate returns strong enough to support current valuations. Until major technology earnings provide an answer, volatility is likely to remain elevated. A disciplined approach—focused on earnings quality, valuation, diversification, and risk management—may be more valuable than chasing the strongest market on any single day.