
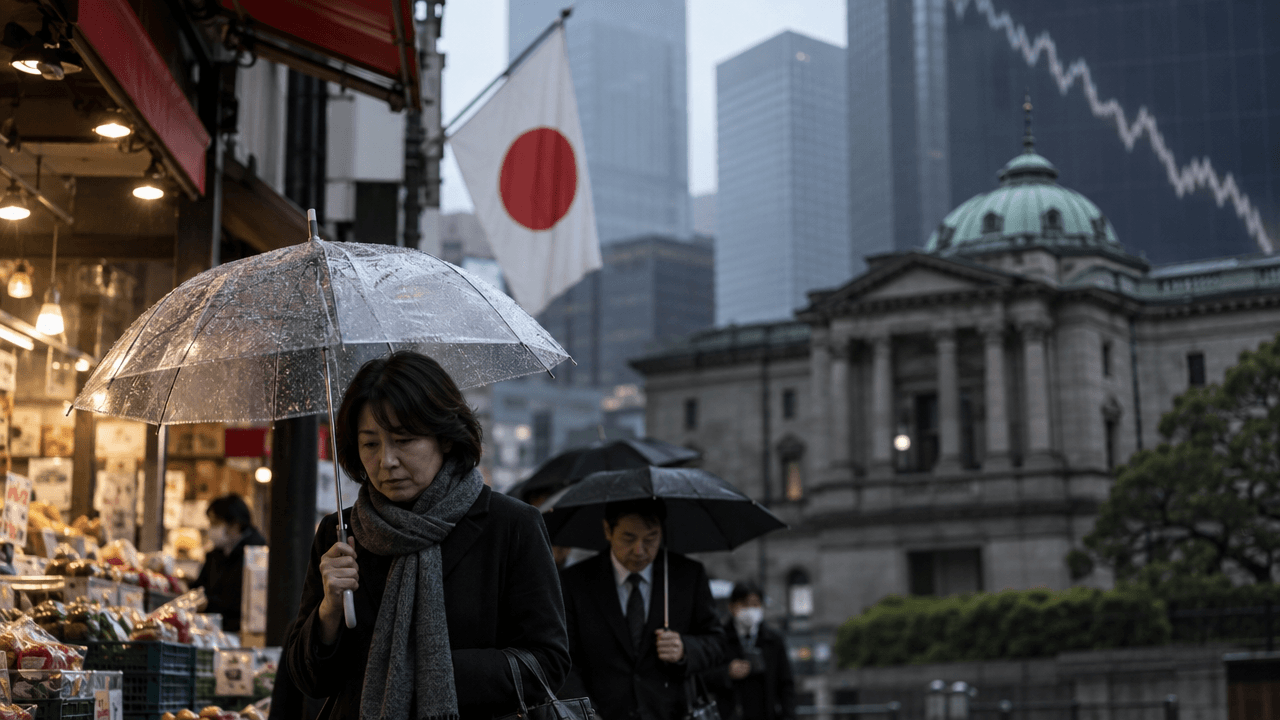
Japan’s economy contracted in the July-September quarter, ending a year of expansion and exposing the fragility of domestic demand. Real gross domestic product declined at an annualized rate of 0.1% from the previous quarter, falling short of economists’ expectations for growth. The result was modest in size, but significant for markets because it arrived as households faced higher prices, elevated energy costs, and increasingly cautious spending. [1]
The data also creates a difficult balancing act for policymakers. The Bank of Japan has been gradually moving away from its long-standing ultra-loose monetary policy, but a weak economy could make further interest-rate increases more politically and economically sensitive. At the same time, inflation driven by imported energy and food costs has not disappeared, leaving the central bank with limited room to ignore price pressures.
Domestic Demand Shows Signs Of Strain
Private consumption, Japan’s largest component of GDP, fell 0.3% from the previous quarter. It was the second consecutive quarterly decline and reflected a combination of poor weather, persistent inflation, and weaker demand for selected consumer goods. [3]
Heavy rain, typhoons, and prolonged wet conditions disrupted travel, outdoor activity, and retail spending during the quarter. Tokyo experienced rain for 37 consecutive days from late August through early October, according to the Japan Meteorological Agency. Weather-related disruptions may eventually prove temporary, but they added to the pressure already facing households. [3]
The more important issue is purchasing power. Prices for energy, food, and imported goods have remained elevated, while the weak yen has increased the cost of goods purchased from overseas. When wages fail to rise faster than prices, consumers tend to delay discretionary purchases, reduce restaurant visits, and become more selective about major spending decisions.
That pattern matters beyond one quarter of GDP. A sustainable recovery requires households to spend with greater confidence, supported by real wage growth and expectations that inflation will moderate. If consumers remain defensive, corporate revenue, hiring, and investment can eventually feel the effects.
Energy Costs And External Pressures
Japan is highly dependent on imported energy, which makes its economy particularly sensitive to oil prices and currency movements. During the latest quarter, rising oil import costs placed additional pressure on the trade balance and household budgets. The weak yen made those imports more expensive in local-currency terms, offsetting some of the benefit from stronger exports. [2]
The external environment has also become more complicated. Japanese exporters face uncertainty from trade restrictions, overseas demand conditions, and geopolitical disruptions affecting commodity and shipping costs. Even when export volumes hold up, higher input and transport expenses can reduce profit margins.
This creates a challenging mix for Japan. Imported inflation can push consumer prices higher without generating stronger domestic growth. In other words, households pay more, but the economy does not necessarily produce more. That distinction is crucial for the Bank of Japan, which wants inflation to be supported by healthy demand rather than primarily by external cost shocks.
There were areas of resilience. Business investment, supported in part by demand related to artificial intelligence and technology, helped cushion the downturn. However, investment strength alone may not be enough to offset weak consumption if households continue to cut back.
What The Gdp Data Means For The Bank Of Japan
The weak GDP reading could complicate expectations for the Bank of Japan’s next policy decision. A contraction normally argues for patience, especially when the weakness is concentrated in consumption. Yet the central bank must also consider inflation, wage trends, and the risk that a weak yen will prolong imported price pressures.
Markets continued to assign a substantial probability to a 25-basis-point rate increase at the December meeting, with LSEG data indicating a probability of approximately 75.6% after the GDP release. [8] That pricing shows investors do not view one soft quarter as sufficient evidence that Japan’s normalization cycle is over.
The key question is whether the weakness is temporary or becoming structural. If poor weather accounts for much of the decline and wages continue to improve, policymakers may look through the latest figures. But if weak spending spreads into services, employment, and underlying wage growth, the case for delaying a rate increase would become stronger.
For traders, headline GDP should therefore be considered alongside upcoming data on household spending, wages, inflation, and business activity. A single quarterly contraction can influence market sentiment, but a sustained deterioration in domestic demand would carry much greater policy significance.
Implications For The Yen And Regional Markets
The yen remained near two-month lows against the dollar as investors assessed whether the data would alter the Bank of Japan’s policy outlook. [13] A weaker economy can reduce expectations for higher Japanese interest rates, which may weigh on the yen by narrowing the expected return advantage of Japanese assets.
However, the currency’s reaction is not straightforward. If investors believe the contraction is temporary and the BOJ will continue tightening, the yen could recover. Conversely, continued weakness combined with high imported inflation could pressure the currency toward the 160-per-dollar area, increasing concern about intervention and financial-market volatility.
Japan’s economic performance also matters across the region. The country is a major importer, exporter, creditor, and supplier of industrial equipment. Slower Japanese household demand could affect regional exporters, while changes in the yen can influence competitiveness across Asian markets. A weaker yen may support Japanese exporters but put pressure on competitors whose products become relatively more expensive.
Practical Takeaways For Traders
The first takeaway is to distinguish temporary disruptions from underlying demand weakness. Weather can distort one quarter, but consecutive declines in consumption deserve closer attention.
Second, monitor the relationship between inflation and wages. Rising prices are less damaging when pay growth is strong enough to preserve household purchasing power. If real wages remain under pressure, consumer weakness may persist.
Third, watch the BOJ’s communication as closely as the rate decision itself. Policymakers will likely emphasize whether the latest contraction changes their confidence in the inflation outlook and the strength of domestic demand.
Finally, treat the yen, Japanese government bonds, and regional equities as connected markets. A weak GDP report can lower rate expectations, weaken the yen, and alter capital flows across Asia, but the reaction may reverse if later data shows that the downturn was temporary.
Japan’s latest contraction is not a crisis, but it is a warning. The economy needs stronger household spending to make inflation sustainable and monetary normalization credible. For now, investors are left balancing disappointing growth against stubborn cost pressures—a combination that makes Japan’s next policy steps especially important.