
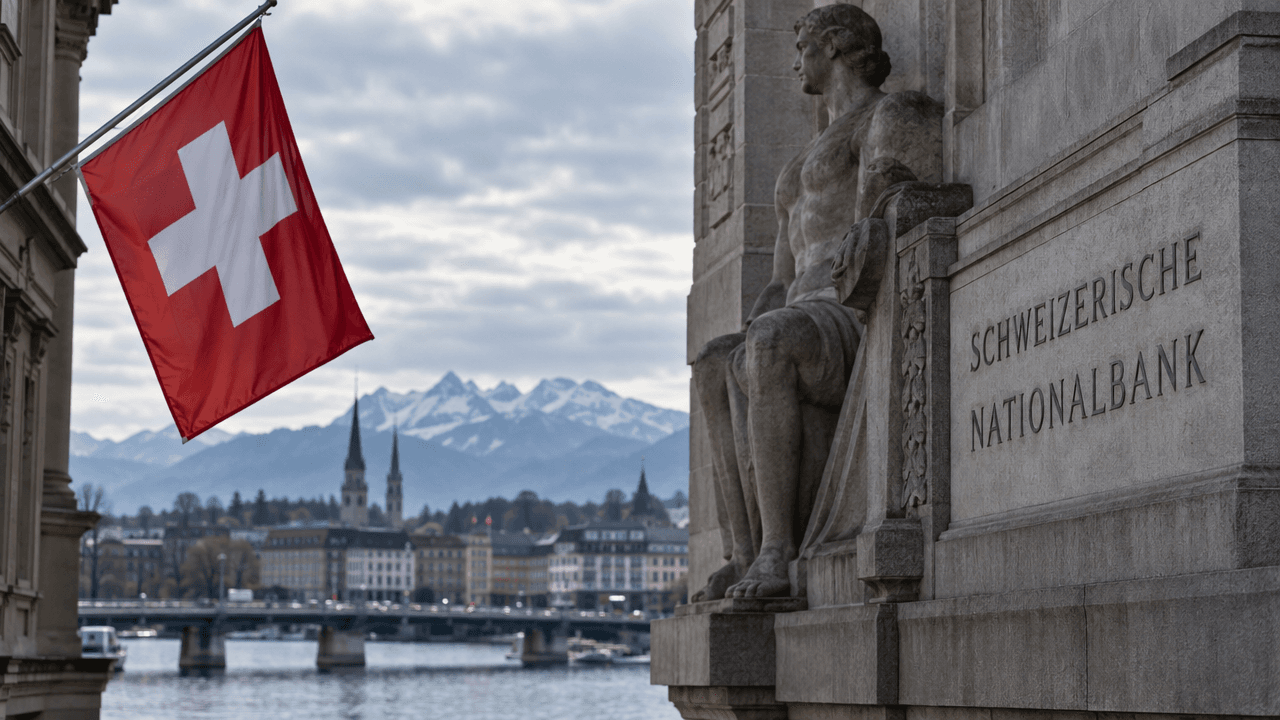
The Swiss National Bank’s decision to hold its policy rate at 0.00% keeps Switzerland anchored at the zero bound while most major central banks remain deep into their tightening cycles.[6][7][9] For traders, that stability is not “no news” – it is a clear policy signal that shapes expectations for the Swiss franc, Swiss assets, and global risk sentiment.[6][7][13] Understanding what this means for CHF crosses and broader market dynamics is essential for anyone trading in a simulated or live environment.
Snb Decision: A Signal Of Continuity
The SNB has maintained its policy rate at 0.00% since mid‑2025, and today’s hold extends that period of ultra‑low rates.[4][6][11] This keeps Switzerland’s benchmark rate the lowest among major central banks, contrasting sharply with rate hikes delivered by the Federal Reserve and the European Central Bank over the past two years.[6][7][9] The decision was widely anticipated, with economists and markets assigning a very high probability to “no change” ahead of the announcement.[3][6][8][10]
Despite headline inflation picking up to around 0.8% in August, price growth remains comfortably within the SNB’s 0%–2% definition of price stability.[6][7][9] The bank continues to argue that the current stance supports both price stability and sustainable economic growth, reducing the need to follow peers into restrictive territory.[1][5][6][11] For traders, the key takeaway is that the SNB is in no rush to tighten and remains committed to a gradual, data‑driven approach.
Why Switzerland Can Stay At Zero
The SNB’s ability to hold at 0% rests on three pillars: low domestic inflation, a resilient economy, and a strong currency that naturally dampens imported price pressures.[6][7][9][13] Even with higher energy costs and geopolitical tensions feeding into global inflation, Swiss consumer prices have stayed subdued relative to most developed markets.[6][9] In this context, raising rates aggressively could unnecessarily slow growth and risk further appreciation of the franc.
At the operational level, the SNB remunerates banks’ sight deposits at the policy rate up to a defined threshold, while applying a 0.25‑percentage‑point discount to balances above that level.[1][4][5][8][11] This tiered system gives the central bank a way to influence money‑market conditions without moving the headline rate, allowing fine‑tuning of liquidity and short‑term funding costs.[1][4][5][11] It is one reason the SNB’s balance sheet and FX operations, rather than the policy rate itself, often do the heavy lifting in Swiss monetary policy.[12][13][15]
The central bank also repeatedly emphasizes its readiness to intervene in the foreign‑exchange market when necessary, especially to counter excessive franc strength that could import disinflation or damage export competitiveness.[12][13][15] Keeping rates at zero preserves flexibility: the SNB can lean more on FX interventions and less on interest‑rate tools when managing external shocks.[12][13][15] For traders, this reinforces the importance of monitoring both policy language and actual intervention patterns, not just the headline rate decision.
Implications For Chf Crosses And Global Markets
A rate hold at 0.00% has direct implications for CHF crosses, especially EUR/CHF, USD/CHF, and GBP/CHF.[6][7][11][13] With the SNB firmly on hold while the ECB and other peers remain comparatively restrictive, interest‑rate differentials still favor foreign currencies over the franc on a carry basis.[6][7][9] However, the franc’s role as a safe‑haven asset means flows can quickly shift toward CHF during bouts of risk aversion, partially offsetting those rate differentials.
The SNB’s decision reinforces a familiar trading regime: currencies with higher yields may retain a carry advantage against CHF, but that trade is always conditional on global risk sentiment and the possibility of SNB FX intervention.[6][7][13][15] In practice, this can mean range‑bound price action in key CHF pairs unless there is a major shock, with the central bank quietly influencing levels through communication and occasional market operations.[12][13][15] Traders should also be aware that the SNB views excessive franc appreciation as a policy problem and has a history of acting decisively when its tolerance threshold is breached.[12][13][15]
Globally, Switzerland’s decision underscores the divergence in monetary cycles: while some central banks continue to fight inflation with higher rates, others, like the SNB, operate in a low‑inflation, low‑rate environment.[6][7][9][11] This divergence shapes capital flows, relative equity valuations, and hedging strategies for international portfolios that include Swiss assets or CHF exposure.[6][9][11]
What Simfi Traders Should Watch Next
For traders using simulated finance environments such as E8 Markets, the SNB’s rate hold offers a real‑world scenario to test macro‑driven strategies without capital at risk. The first focus point should be the evolution of inflation relative to the SNB’s 0%–2% target range.[6][7][9] If Swiss inflation drifts persistently toward the upper end, market pricing for future SNB hikes could rise, altering expectations embedded in CHF forwards and swaps.[11]
Second, closely watch communications from SNB officials, particularly any shift in tone around the franc’s valuation or the global risk backdrop.[6][7][12][13] A stronger emphasis on FX interventions or concerns about imported inflation could precede action in the currency market.[12][13][15] SimFi traders can build scenarios around these communications – for example, modeling how EUR/CHF might react to hints of reduced intervention versus more aggressive SNB activity.
Third, monitor the spread between Swiss yields and those of major peers, especially in the euro area and the United States.[6][7][9][11] These rate differentials not only influence carry trades but also serve as a barometer for relative monetary stance and investor appetite for Switzerland’s low‑yield, low‑inflation environment.[6][9][11] Simulated portfolios that combine CHF exposure with higher‑yielding currencies can help traders understand how carry, volatility, and safe‑haven flows interact over time.
Key Takeaways For E8 Markets Traders
1. The SNB’s hold at 0.00% is not a surprise, but it is a clear confirmation that Switzerland remains committed to a very accommodative stance while inflation stays within its comfort zone.[1][5][6][7][9][11]
2. The operational framework – tiered remuneration of sight deposits and a standing willingness to intervene in FX – means the SNB can fine‑tune conditions without moving the headline rate.[1][4][5][8][11][12][13][15]
3. CHF crosses remain driven by a mix of interest‑rate differentials, safe‑haven flows, and expectations of SNB behavior in the currency market, rather than by the policy rate alone.[6][7][9][11][13][15]
4. For SimFi traders, this environment is ideal for practicing macro‑aware strategies: building scenarios around inflation, central bank communication, and global risk sentiment, and then observing how CHF pairs respond.
In short, the SNB’s decision to keep its policy rate at 0.00% extends a period of monetary stability that belies a complex underlying framework of FX management, liquidity tools, and inflation targeting.[1][4][5][6][7][9][11][12][13][15] Traders who look beyond the unchanged headline rate and focus on these mechanics will be better equipped to interpret CHF moves – whether in a simulated environment or, eventually, in live markets.