
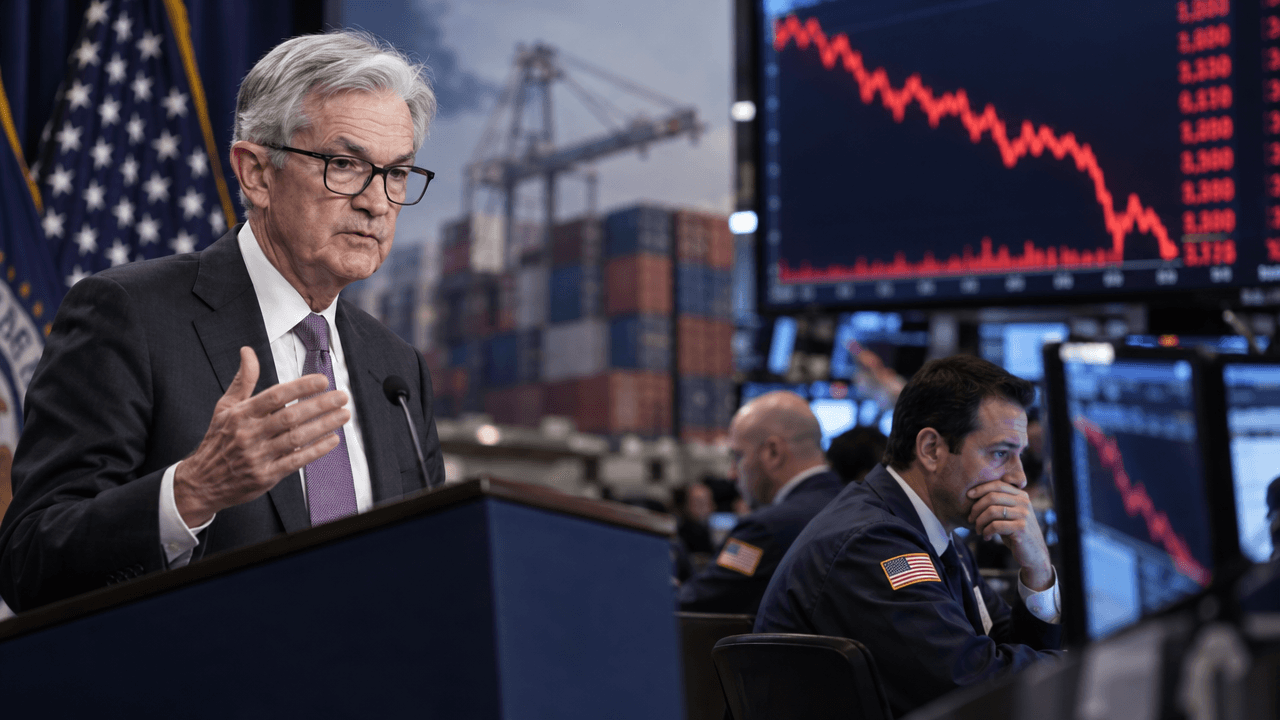
US equities suffered a sharp retreat after Federal Reserve Chair Jerome Powell warned that economic growth appeared to be slowing and that larger tariffs could push inflation higher while weakening economic activity. The Dow Jones Industrial Average fell 1.73%, the S&P 500 declined 2.24%, and the Nasdaq Composite dropped 3.07%, with technology stocks bearing the heaviest pressure. [1]
The sell-off reflected more than a single disappointing session. Investors were forced to reconsider the outlook for corporate earnings, interest rates, consumer demand, and future economic growth. Powell’s comments highlighted a difficult combination for markets: inflation may remain elevated even as the economy loses momentum.
WHY POWELL’S WARNING MATTERED
Financial markets typically respond positively when slower growth increases the likelihood of interest-rate cuts. However, that relationship becomes more complicated when inflation is also expected to rise. Tariffs can increase the cost of imported goods, parts, and raw materials, forcing companies to choose between absorbing higher expenses or passing them on to customers.
Powell indicated that larger-than-expected tariffs could produce both higher inflation and slower growth. [4] This creates a challenging environment for the Federal Reserve. Cutting interest rates may support economic activity, but easier policy could also make it more difficult to contain inflation. Keeping rates high may restrain prices, but it could further weaken business investment, hiring, and household spending.
For investors, the concern is that the central bank may have less flexibility than previously expected. A weakening economy does not automatically guarantee near-term rate cuts if price pressures remain persistent.
Why Technology Stocks Fell The Most
The Nasdaq’s 3.07% decline was significantly larger than the Dow’s 1.73% drop. [1] This performance reflects the sensitivity of growth-oriented companies to interest rates and economic expectations.
Technology and other high-growth stocks often derive a large portion of their perceived value from profits expected years into the future. When bond yields rise or investors expect rates to remain elevated, those future earnings become less attractive in today’s dollars. As a result, expensive technology shares can experience sharp declines even when their long-term business prospects remain intact.
The technology sector also faced company-specific pressure. Nvidia declined after warning about substantial charges linked to new restrictions on chip exports to China, adding another layer of uncertainty for semiconductor and artificial intelligence stocks. [1] The combination of trade restrictions, tariff concerns, and higher-rate expectations encouraged investors to reduce exposure to some of the market’s most crowded positions.
What The Selloff Says About Market Sentiment
The market reaction suggests that investors were already operating with limited tolerance for negative surprises. Tariff uncertainty has the potential to affect several parts of the economy at once, including prices, supply chains, profit margins, and international trade.
Risk-sensitive currencies also came under pressure as investors moved toward more defensive positions. When uncertainty rises, market participants often reduce exposure to assets that depend heavily on strong global growth, including cyclical equities, emerging-market currencies, and commodities tied to industrial demand.
The decline in the major indexes does not necessarily confirm that a recession is imminent. Instead, it shows that markets are repricing the probability of weaker growth and a more complicated Federal Reserve response. Volatility can increase when investors receive conflicting signals: slowing activity may support lower rates, while tariff-driven inflation may delay them.
Practical Lessons For Traders
Traders should avoid treating a sharp one-day decline as a complete forecast of future market direction. The more useful question is whether the sell-off develops into a broader trend supported by deteriorating economic data, declining earnings estimates, or persistent weakness in market breadth.
Several indicators deserve close attention
1. Inflation data can reveal whether tariff-related price increases are temporary or becoming more widespread.
2. Labor-market reports can show whether slower growth is beginning to affect hiring, wages, and household income.
3. Corporate earnings guidance may indicate whether businesses are absorbing higher costs or passing them on to consumers.
4. Treasury yields and interest-rate futures can provide clues about how markets are interpreting the Federal Reserve’s next steps.
5. Market breadth can help distinguish a concentrated technology correction from a broader equity downturn.
Risk management is especially important during policy-driven volatility. Traders may consider reducing excessive leverage, defining exit levels before entering positions, and avoiding decisions based solely on intraday headlines. Diversification across sectors and asset classes can also help limit dependence on one economic outcome.
The Broader Outlook
The central issue for markets is whether the economy experiences a temporary slowdown or a more durable loss of momentum. If inflation moderates while growth remains positive, equities could stabilize as investors regain confidence in a gradual policy adjustment. If inflation stays elevated while employment and demand weaken, markets may face a more difficult period of repricing.
Powell’s remarks did not provide a simple policy signal. Instead, they emphasized the uncertainty confronting policymakers. Tariffs may raise prices, reduce trade activity, and pressure corporate margins at the same time. That combination makes traditional market assumptions less reliable.
US equities retreated because investors were reminded that economic growth, inflation, trade policy, and interest rates are closely connected. For traders and investors, the key takeaway is to focus less on predicting the next market move and more on preparing for multiple scenarios. A disciplined approach to position sizing, diversification, and economic data can be more valuable than reacting to every headline.