
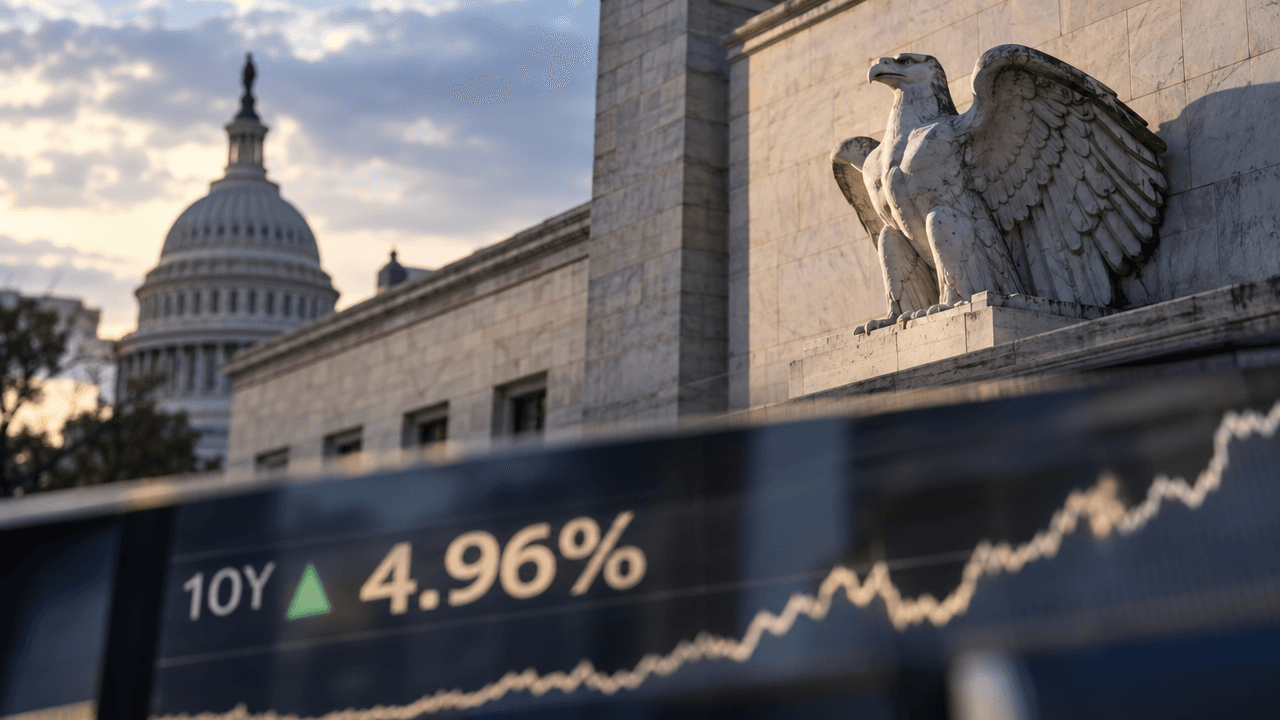
U.S. Treasury yields moved higher after stronger-than-expected labor-market data reinforced expectations that the Federal Reserve may need to keep interest rates restrictive for longer. The benchmark 10-year Treasury yield climbed to approximately 4.96%, while the two-year yield rose to about 4.63%, reflecting renewed concerns that inflation may not cool quickly enough to justify near-term policy easing. [2][6]
The immediate catalyst was the September Job Openings and Labor Turnover Survey, or JOLTS. Job openings increased to 7.523 million from a revised 7.190 million in August, exceeding expectations and reaching the highest level in four months. The number of workers quitting their jobs also rose to 3.365 million, its highest level since March 2025. [2]
For markets, the message was clear: Businesses continue to demand labor, workers retain enough confidence to change jobs, and the economy may be more durable than recent cooling signals suggested.
Why The Jolts Report Matters
JOLTS is closely watched because it provides information beyond the monthly employment report. It tracks job openings, hires, layoffs, and quits, helping investors assess both labor demand and worker confidence.
A high level of job openings can indicate that employers are still competing for workers. When companies struggle to fill positions, wages may remain elevated, potentially adding pressure to service-sector inflation. A rising quits rate can point to confidence among employees that comparable or better opportunities are available elsewhere.
That does not mean the labor market is overheating. Hiring, wage growth, and participation trends must also be considered. However, the latest figures challenge the idea that employment conditions are deteriorating rapidly. Federal Reserve officials may interpret that resilience as giving them more time to prioritize price stability over economic support.
The Federal Reserve has a dual mandate: maximum employment and stable prices. If employment remains broadly healthy while inflation is still elevated, policymakers have less incentive to reduce interest rates quickly.
Why Treasury Yields Rose
Treasury yields represent the interest rates investors demand to hold government debt. They move in response to expectations for inflation, economic growth, Federal Reserve policy, and the supply and demand for bonds.
The two-year Treasury yield is especially sensitive to anticipated changes in the federal funds rate. Its rise toward 4.63% suggests investors were adjusting expectations for the path of short-term policy. If traders believe the Fed will keep rates high—or potentially raise them again—short-term yields typically respond first.
The 10-year yield reflects a broader combination of factors, including expected future interest rates, long-term inflation, economic growth, and the compensation investors require for holding longer-duration bonds. Its move toward 4.96% indicates that markets are pricing a more persistent higher-rate environment.
Recent Federal Reserve analysis has also linked higher Treasury yields to expectations for a stronger policy-rate path and greater confidence in labor-market stability. [5][9]
What Higher Yields Mean For Markets
Higher Treasury yields increase the return available from relatively low-risk government securities. That can make bonds more attractive compared with stocks, particularly when equity valuations are elevated.
Growth-oriented companies may face the greatest pressure. Their valuations often depend on profits expected several years in the future. When bond yields rise, those future earnings are discounted at a higher rate, which can reduce the present value investors assign to them.
Higher yields can also raise borrowing costs for households and businesses. Mortgage rates, corporate debt costs, auto loans, and other forms of credit may become more expensive. Over time, that can slow investment, housing activity, and consumer spending.
Financial institutions may benefit from higher interest income in some circumstances, especially if loan rates adjust faster than deposit costs. However, persistently high rates can also reduce loan demand and increase the risk that borrowers struggle to service debt.
For currency markets, higher U.S. yields may support the dollar by making dollar-denominated assets more attractive to international investors. A stronger dollar can lower the domestic cost of imported goods, but it may also create challenges for U.S. multinational companies and emerging-market borrowers with dollar liabilities.
What Traders Should Watch Next
The JOLTS report is important, but it is only one piece of the policy outlook. Traders should compare it with payroll growth, unemployment claims, wage data, inflation readings, consumer spending, and business surveys.
The next major test will be whether stronger labor demand is translating into renewed wage and price pressure. If inflation remains sticky while employment data stay firm, expectations for a “higher-for-longer” policy stance could strengthen further.
Market participants should also monitor the spread between two-year and 10-year yields. Changes in that relationship can offer clues about whether investors are focused primarily on near-term Fed policy or longer-term growth and inflation risks.
For SimFi traders, the practical lesson is to avoid treating a single data release as a complete market signal. A disciplined approach includes identifying the likely economic surprise, determining which assets are most sensitive to it, and planning risk around potential reversals. Treasury yields can move sharply when subsequent data contradict the initial interpretation.
The Bigger Picture
The rise in Treasury yields shows how quickly labor-market data can reshape interest-rate expectations. Strong job openings and an improved quits rate do not guarantee another Fed hike, but they reduce pressure on policymakers to ease policy immediately.
For investors and traders, the central question is no longer simply whether the economy is slowing. It is whether growth is slowing enough to bring inflation under control without requiring additional monetary restraint.
As long as labor demand remains resilient and inflation stays above the Federal Reserve’s comfort zone, Treasury markets are likely to remain sensitive to every major employment and price report. The latest JOLTS figures therefore represent more than a strong monthly release: they are a reminder that the path toward lower rates may be slower, more volatile, and more dependent on incoming data than many market participants had expected.